

ECONOMY & DEVELOPMENT
COST-OF-LIVING CRISIS FUELS DEBT TRAP AS DIGITAL LOAN RATES NEAR 50%/MONTH
Nigeria’s worsening cost-of-living crisis is pushing more households towards digital lending platforms, with concerns mounting over interest rates that can approach 50 per cent monthly and leave financially struggling borrowers trapped in a cycle of debt.
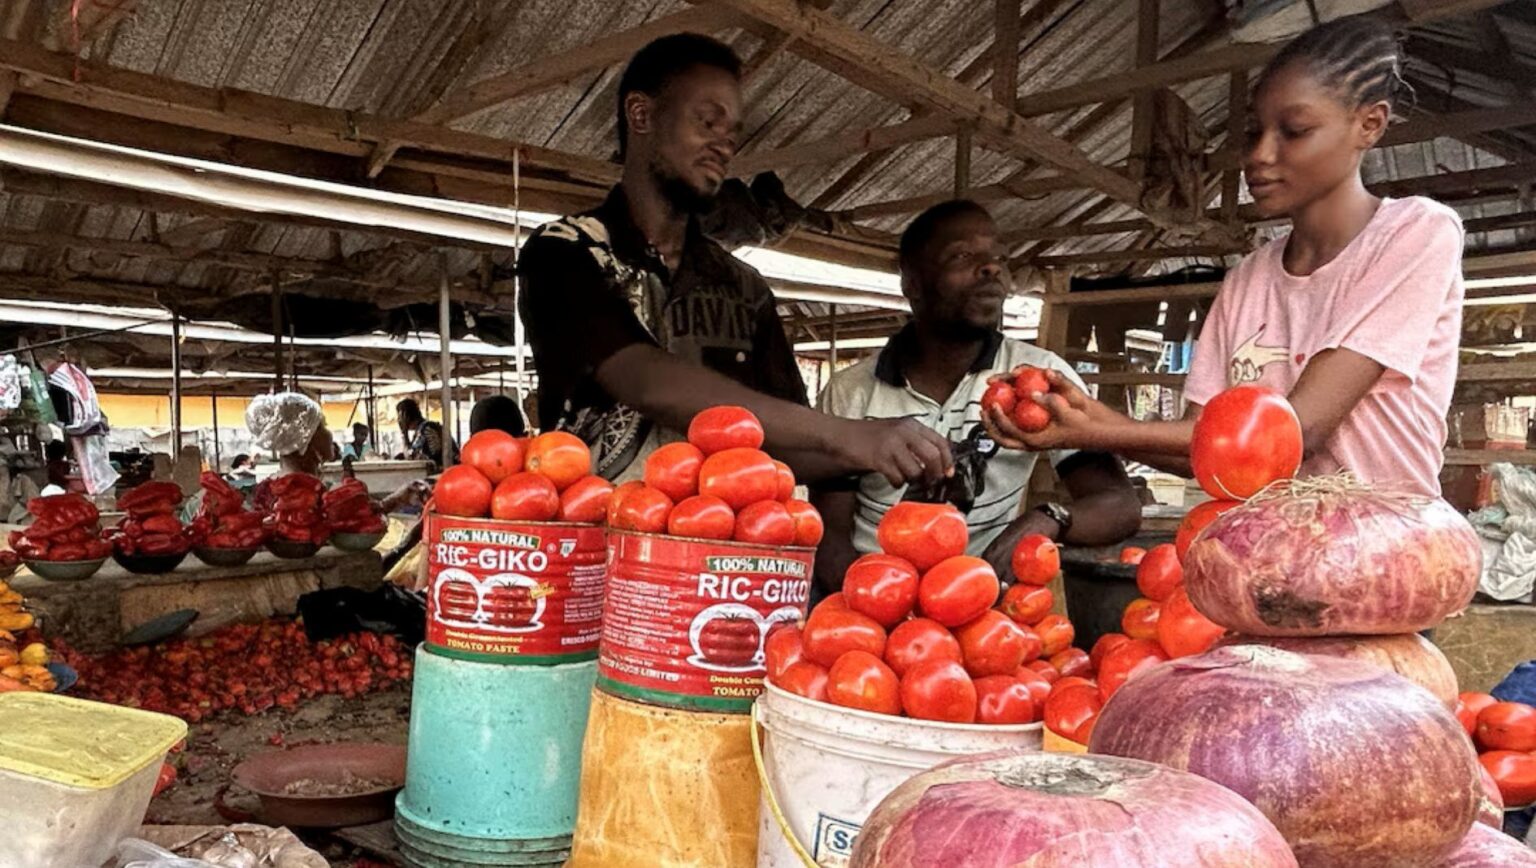
As food prices, transportation costs, rent and other essential expenses continue to put pressure on household budgets, many Nigerians are increasingly turning to instant loan applications to meet their immediate financial needs.
Digital loan disbursements in Nigeria reached $1.63 billion in 2025, reflecting the growing dependence on short-term credit. However, the cost of accessing these loans has become a major concern.
An investigation by The Guardian found that OPay's lending platform, EaseMoni, charges low-risk borrowers approximately 18.9 per cent monthly interest. Meanwhile, some new PalmPay customers have reportedly received loan offers carrying daily interest rates of 1.5 per cent, which could translate to an effective monthly rate of about 56.3 per cent when compounded daily.
Borrowers with weaker credit ratings may face even higher charges, with some digital lenders reportedly imposing monthly interest rates approaching 25 per cent.
The situation becomes more difficult when borrowers miss repayment deadlines. Some lenders apply additional penalties to outstanding balances, meaning customers who default for extended periods could eventually repay several times the amount originally borrowed.
The expansion of digital lending has also attracted attention because of the growing number of Nigerians borrowing to finance basic consumption rather than business activities. This raises concerns that loans intended to provide temporary relief may instead deepen financial difficulties.
OPay reportedly accounted for 57.4 per cent of Nigeria's digital credit disbursements in 2025, making it one of the dominant players in the sector. Its growing lending operations have also exposed the company to increased loan defaults and credit risks.
Consumer protection advocates are calling for stronger regulatory intervention, clearer disclosure of borrowing costs and improved oversight of digital lending platforms.
The Federal Competition and Consumer Protection Commission has introduced regulations covering digital lending practices, but concerns remain over excessive interest rates, aggressive debt recovery methods and consumer privacy.
Financial analysts warn that access to credit should not become another burden for struggling households. They argue that affordable lending, improved wages and measures to reduce the cost of essential goods are necessary to prevent more Nigerians from falling into debt.
The growing digital loan crisis highlights a difficult reality: while instant loans can help people handle emergencies, borrowing at extremely high interest rates may turn temporary financial problems into long-term economic hardship.